
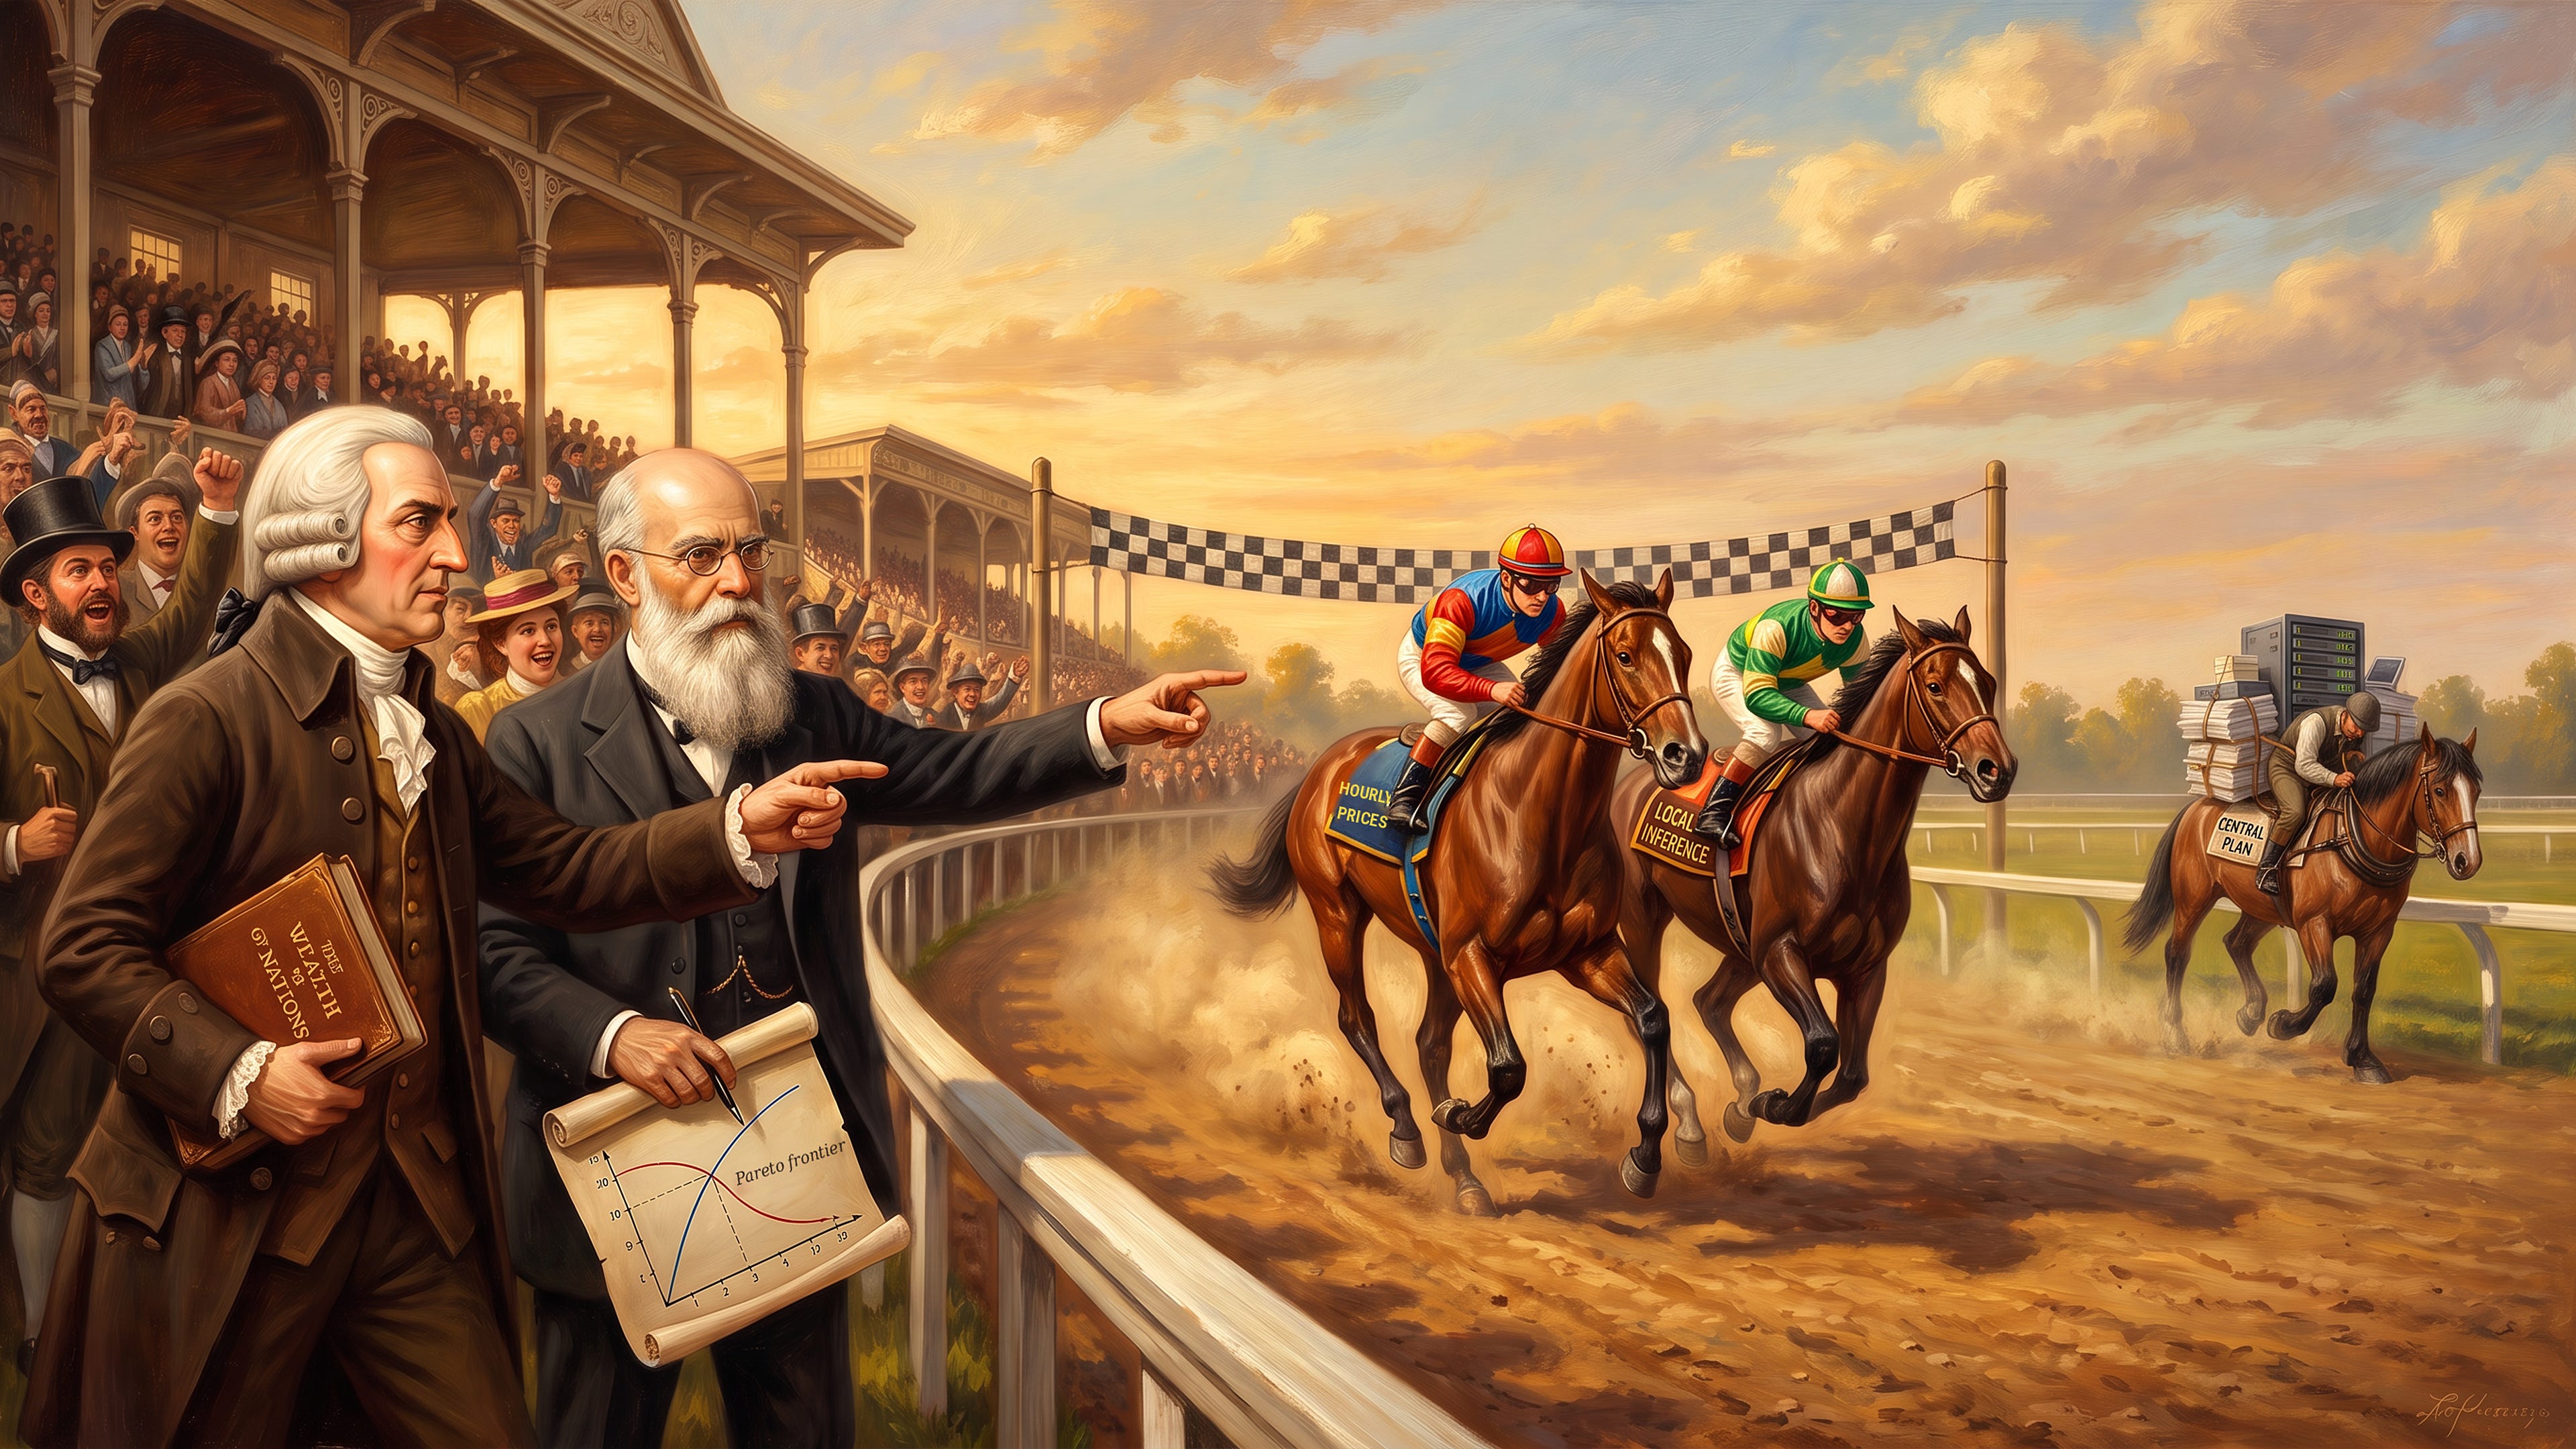
Last week, the chip index had its worst day since March 2020 and roughly $2.5 trillion of value disappeared before a partial rebound (NBC News, CNN). The same week, the hourly rate for an Nvidia B200 on Ornn’s trade-based index settled about a fifth higher than a month earlier (The Tech Bag). Buyers paying cash for compute by the hour bid it up while investors dumped the companies that had promised to supply it by the decade. I read that split as the clearest signal of the year: buyers are still paying up for intelligence, and investors have stopped trusting the planners who decided in advance how much of it would be needed.
Regular readers have watched this argument assemble. The Gravity of Good Enough took the black hole from The Infinite Dawn and applied Gresham’s law to tokens, so that the cheaper coin wins wherever two models clear the same bar. The Bounded Frontier of Agentic ROI drew the curve of price against capability that buyers sort themselves along. The Ledger Learns to Speak Every Currency asked why Stripe would buy OpenRouter and concluded that the router gets paid whoever wins. Last week supplied the missing piece, which is what happens to the companies that bet against that sorting by locking in capacity and customers years ahead.
The Hourly Price of Compute Rose While the Planners Fell
Follow the cash and the selloff splits in two. On the open market, where anyone can rent a GPU for an hour, prices have climbed for four months: the GPU Rental Price Index, which checks published rates across more than 20 providers every day, sat about 11% above its July baseline last Sunday (GPU Rental Prices). Buyers paying by the hour are still bidding against each other for the marginal chip. The damage landed elsewhere, on businesses financed against long contracts, with CoreWeave and Nebius each losing about half their value between early October and last Friday (24/7 Wall St.).
The same week supplied a small, telling detail. Microsoft let a 2023 deal to rent AI capacity from Oracle lapse and has been switching the servers off, because the older Nvidia chips inside no longer meet its needs (Reuters via Bellingham Herald, Crowdfund Insider). Hardware rented as a strategic asset in 2023 became surplus inside a single contract term. A free market does that to chips when the frontier moves every few months, and every decade-long capacity plan carries the same exposure on its books. Rising hourly rates and idle older fleets point the same way, toward a market that pays whoever can reprice fastest.
Oracle Built a Utility for a Market That Wants an Exchange
Oracle is the purest test of the planning model, and investors have graded it. The company built its AI cloud around a backlog in which OpenAI accounts for roughly half of remaining obligations, by S&P Global’s estimate (Moat Explorer), and financed the buildout outside its own cash flow, which was negative by more than $20 billion in fiscal 2026 (Real Investment Advice). Last Monday it raised $20 billion, half in stock sold at a discount and half in bonds with coupons reaching 8.65%, and the shares closed more than 60% below their September 2025 peak (Yahoo Finance).
The problem sits in the design more than the execution. A utility works when the regulator fixes the price and the customers cannot leave, and Oracle has tried to recreate those conditions privately: one anchor tenant, multi-year commitments, and capacity sized to a forecast. AI compute has neither condition. Customers can leave on two weeks’ notice through any router, and the hardware loses value faster than the contract runs, as Microsoft just demonstrated with Oracle’s own servers. A centrally planned supplier in a market that clears every hour will keep finding itself on the wrong side of the price, and Oracle’s capital raises are the cost of staying on that side.
OpenAI, Anthropic and Nvidia Carry the Planners’ Risk Too
The frontier labs and their chip supplier sit closer to Oracle than their valuations suggest. Anthropic’s amended IPO filing shows about $895 billion in compute and infrastructure commitments (Filing Insights), with its core cloud deals running into the 2030s and payable regardless of usage, against roughly $1 of committed customer spend for every $23 of compute it has promised to buy (Forrester). OpenAI cut its funding target by a third to $20 billion as investors pulled back (Bloomberg via Yahoo Finance). Nvidia has nearly $50 billion invested in frontier labs, guarantee obligations above $100 billion, and customers taking longer to pay (Yahoo Finance).
Anthropic’s own filing contains the connection. Despite all those long contracts, the company spent $5 billion in the third quarter buying short-term compute at prices well above its contracted rates, and it expects to buy more (Forrester). The most successful lab of the year planned its capacity years ahead and still had to go to the hourly market when demand arrived in a shape the plan did not predict. The labs may well be in peril, and if they are, the cause will be the fixed obligations they took on to guarantee supply, while the demand underneath them keeps rising.
Adam Smith Named the Architects of This System in 1776
Readers who know The Wealth of Nations for the invisible hand tend to skip its sharpest passages, which are warnings about the merchants who profit most from markets. At the end of his chapter on rent, Smith put the warning in one line: “To widen the market, and to narrow the competition, is always the interest of the dealers” (The Wealth of Nations, Book I, Chapter XI). Widening the market, he allowed, often suits the public. Narrowing the competition always works against it, and serves only to let the dealers “levy, for their own benefit, an absurd tax upon the rest of their fellow-citizens.” He added that any new regulation of commerce proposed by that order of men deserved “the most suspicious attention.”
The AI buildout has been widening the market and narrowing the competition at the same time, with instruments Smith would have filed under the mercantile system. Compute contracts that run into the 2030s and are payable whether or not the capacity gets used, minimum-spend clauses pushed onto enterprise customers, and Broadcom arranging a $42 billion loan solely to finance rent on its own equipment, all described by Forrester, lock supply and demand together before any price can form. Smith concluded in Book IV that the “principal architects” of the mercantile system were “our merchants and manufacturers,” and that under it “the interest of the consumer is almost constantly sacrificed to that of the producer” (The Wealth of Nations, Book IV, Chapter VIII). The companies that talk most about AI abundance are drawing up its mercantile system, and last week investors began charging them for it.
Pareto’s Frontier Sets the Price of Intelligence
Vilfredo Pareto supplies the tool for reading what replaces that system. Pareto trained as an engineer in Turin, became a director of an Italian railway, succeeded Léon Walras in the chair of economics at Lausanne in 1893, and in his 1906 Manual of Political Economy defined the condition economists still name after him: an allocation is optimal when no one can be made better off without making someone else worse off (Econlib, Britannica). He came to economics from railway and ironworks management, and the definition carries an engineer’s respect for trade-offs that no amount of planning can wish away. Pareto also spent years writing pamphlets against protectionism, which he ranked with militarism as the two greatest enemies of liberty.
Applied to AI models, the idea becomes a curve. A model sits on the Pareto frontier when no rival is both cheaper and more capable, and a buyer’s job is to pick the point on that curve each task needs, paying for capability only where the task rewards it. The Bounded Frontier of Agentic ROI used that curve to ask where agents pay for themselves, and here it describes how an entire market prices intelligence. Given his pamphlets, the man whose name sits on the curve would have had little patience for anyone fixing a price on it in advance.
OpenRouter’s October traffic shows buyers moving along that curve in real time. The platform routed roughly 25 times more tokens in October than in January (OpenRouter), and the way those tokens moved is the argument in miniature. When Anthropic and OpenAI shipped their newest frontier models in late September, the open-weight share of paid traffic fell to about half, and two weeks later it was back above 70%, mostly on DeepSeek V4.1 Flash. Developers tried the new top of the curve on everything, kept it for the work that justified the price, and sent the rest back down to the cheapest model that could do the job, all inside a fortnight.
That motion is how a free market sets the frontier premium, task by task, without anyone negotiating it in advance. By OpenRouter’s account, DeepSeek’s cheap model leads most coding and agent tasks by volume while Claude Opus 5.5 leads most of the board by spend. Menlo Ventures found the same split in enterprise budgets, with frontier models taking nearly two thirds of spending and the mid-priced closed models losing more than half their share of tokens even after deep price cuts (Menlo Ventures). Buyers pay a real premium where a mistake is expensive and almost nothing where volume is the point, and the premium holds only as long as the capability gap does.
The Exchange Is Already Built
Put the pieces from August next to the pieces from last month and the outline of a market appears. OpenRouter matches each request to a model at a price, which makes it the order book. Stripe, which agreed to buy OpenRouter to help businesses optimize token routing and usage, settles the payment on every match. Modal supplies the capacity underneath without asking anyone to commit to it: the company passed $1 billion in annualized revenue in October, growing more than 15 times year over year, on a pool of GPUs that spans more than 20 clouds and offers clusters “with no capacity commitment” (Modal). Together they look like the exchange, the clearing house and the floating supply of a commodity market.
Each of these companies earns more when forecasts miss. A router earns more when traffic shifts, a payment network earns on every transaction whichever model wins, and an elastic capacity pool earns when demand arrives in an unexpected shape, which is the shape Anthropic just paid a premium to meet. They profit from the same uncertainty that has pushed Oracle’s credit rating to one notch above junk. Investors who sold everything with “AI” in the description on Thursday sold the planners and the companies that run the exchange together, and the two have opposite exposure to the thing that frightened them.
Local Inference Is Here, and Apple Is Waiting at the Fab
Some of that demand is leaving the data center entirely. Apple’s machine learning team showed in October that four M5 Ultra Mac Studios can run Muse Spark Open, a model of more than 800 billion parameters, faster than a person reads (Apple Machine Learning Research). Perplexity now splits tasks on the Mac, sending planning and research to the cloud while a local model handles private files and the actions that touch them (Perplexity). Every token that runs on a desk is one that required no data-center plan, and the buyer paid for that capacity once, at retail, with no contract.
Apple is also the company best placed to absorb any manufacturing capacity a slower buildout frees up. Brad Gerstner has estimated that a quarter to a third of next year’s data-center construction could face delays under the new state governments, which would ease the memory shortage that has been squeezing Apple’s margins (The Motley Fool via Yahoo Finance), and Apple has already raised its supplier purchase obligations by $33 billion to secure components (TheStreet via Yahoo Finance). I would not bet on that slack appearing, since hourly GPU prices are still rising and memory makers are locking in long-term pricing. If it does appear, Apple will be first in line for it.
Investors Can Now Ask the Top of the Food Chain to Let Prices Decide
The tilt after last week runs toward the buyers of capital. OpenAI had to shrink its raise, Anthropic’s prospective investors are discussing a valuation well below the $2 trillion that circulated earlier (Reuters), and Forrester is telling enterprise buyers to keep AI contracts short and trade any commitment for price protection. Each of those hands bargaining power to whoever supplies the capital or signs the purchase order, and that power can be used to ask the companies at the top of the food chain to stop deciding in advance how much capacity gets built and what the frontier premium should be, and to let hourly prices and routing settle both. Smith’s maxim from Book IV, that “consumption is the sole end and purpose of all production,” is the test to put to every capacity plan they bring to market.
Smith and Pareto, writing a century apart, would have agreed on the diagnosis: producers who fix capacity and price in advance end up taxing their own customers, and buyers left free to sort themselves find the frontier faster than any plan can. I am not claiming the labs or Nvidia will survive the adjustment intact, that the buildout cannot overshoot, or that local inference will replace the data center. My claim is narrower: last week punished central planning in AI infrastructure, the exchange that replaces it is already operating, and the companies built for it are the ones to own.
For the executive signing off on 2027 budgets, three decisions follow. First, buy compute and models the way Modal and OpenRouter sell them, on short terms with the right to move, because every multi-year commitment you sign takes a slice of your supplier’s planning risk onto your own books. Second, route your workloads across frontier and open-weight models through a layer you control, so that a launch week lowers your costs instead of resetting your contracts. Third, move private and repetitive work onto hardware you already own, since a Mac Studio on a desk carries no counterparty and no renewal date.
Alan Eyzaguirre writes about AI, capital markets, and corporate strategy as a Silicon Valley entrepreneur and corporate strategist.